


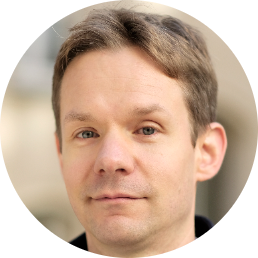
Prof. Dr. Max Bruche
- Name
- Prof. Dr. Max Bruche
- Status
- Prof.
- max.bruche (at) hu-berlin.de
- Web Adresse
- https://www.wiwi.hu-berlin.de/en/professuren/bwl/finance/
- Einrichtung
-
Wirtschaftswissenschaftliche Fakultät →Finanzierung
- Funktion / Sachgebiet
- Leiter
- Sitz
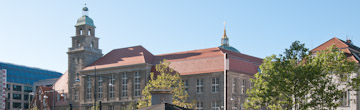
- Institutsgebäude, Dorotheenstraße 1 , Raum 307
- Telefon
- +49 30 2093-99472
- Postanschrift
- Unter den Linden 6, 10099 Berlin Lehrveranstaltungen
- ORCID
- 0000-0002-0346-2644
-
Vita
Max Bruches Forschung konzentriert sich auf Finanzintermediation und Corporate Finance, mit besonderem Schwerpunkt auf Fremdkapitalmärkten. Seine Arbeiten sind unter anderem im Review of Financial Studies, im Journal of Financial Economics, im Journal of Monetary Economics und in Management Science erschienen. Vor seinem Wechsel an die Humboldt-Universität zu Berlin war er an der Bayes Business School (ehemals Cass Business School) in London und am CEMFI in Madrid tätig; darüber hinaus hatte er Gastpositionen bei der Federal Reserve Bank of New York, der Europäischen Zentralbank und Lehman Brothers inne. Er wurde an der London School of Economics in Finance promoviert und erwarb einen MPhil in Economics sowie einen BA in Politics, Philosophy and Economics an der University of Oxford.
-
Publikationen
- "Dealer Funding and Market Liquidity," mit John C. F. Kuong.
Accepted at Management Science
[Paper on SSRN] - "Pipeline Risk in Leveraged Loan Syndication," mit Frederic Malherbe and Ralf Meisenzahl.
Review of Financial Studies, December 2020, 33(12), 5660-5705.
[Paper] [Paper on SSRN] [Open Access paper at Oxford University Press] - "Debt Maturity and the Liquidity of Secondary Debt Markets," mit Anatoli Segura.
Journal of Financial Economics, June 2017, 124(3), 599-613.
[Paper] [Paper on SSRN] [Paper on ScienceDirect] [Online Appendix] - "Preventing Zombie Lending," mit Gerard Llobet.
Review of Financial Studies, March 2014, 27(3), 923-956.
[Paper] [Paper on SSRN] [Paper at Oxford University Press] [Non-technical description on VoxEU] - "Creditor Coordination, Liquidation Timing, and Debt Valuation."
Journal of Financial and Quantitative Analysis, October 2011, 46(5), 1407-1436.
[Paper] [Paper on SSRN] [Paper at Cambridge Journals Online] - "A Structural Model of Debt Pricing with Creditor-Determined Liquidation," mit Hassan Naqvi.
Journal of Economic Dynamics and Control, May 2010, 34(5), 951-967.
[Paper] [Paper on SSRN] - "Recovery Rates, Default Probabilities, and the Credit Cycle," mit Carlos González-Aguado.
Journal of Banking and Finance, April 2010, 34(4), 713-723.
[Paper] [Paper on SSRN] [Presentation] [Sample Matlab Code] [Web appendices] - "Deposit Insurance and Money Market Freezes," mit Javier Suárez.
Journal of Monetary Economics, January 2010, 57(1), 45-61.
[Paper] [Paper on SSRN] [Presentation] [Non-technical description on VoxEU]
- "Dealer Funding and Market Liquidity," mit John C. F. Kuong.